Personal Guarantor Insolvency Under IBC: Legal Process
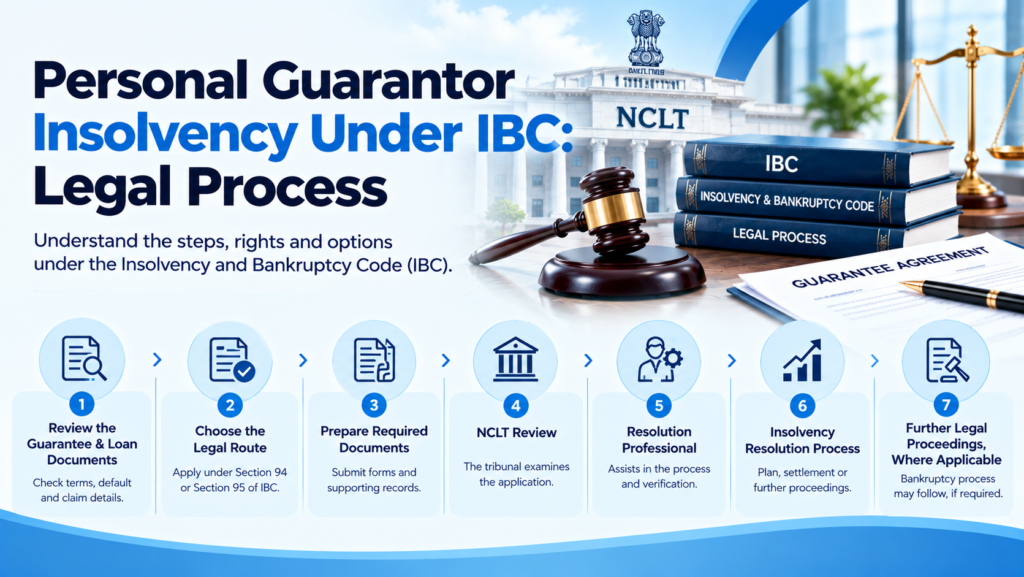
When a company takes a loan from a bank or financial institution, its directors or promoters may provide a personal guarantee to support the borrowing. If the company fails to repay the loan, the lender may take legal action against the personal guarantor, subject to the guarantee terms and applicable law. The Personal Guarantor Insolvency Under IBC framework provides a legal process for dealing with insolvency involving individuals who have guaranteed debts of corporate borrowers. It is particularly relevant to company directors, promoters, business owners, and other individuals who have signed personal guarantees.. What Is Personal Guarantor Insolvency Under IBC? Personal Guarantor Insolvency Under IBC refers to the insolvency resolution and related bankruptcy framework applicable to individuals who have provided personal guarantees for corporate debtors under the Insolvency and Bankruptcy Code, 2016. A personal guarantor is an individual who promises to meet a borrower’s obligations if the borrower fails to do so, subject to the terms of the guarantee and applicable law. For example, suppose a company borrows ₹5 crore from a bank, and its director provides a personal guarantee. If the company defaults, the bank may pursue remedies against the company and the guarantor, depending on the circumstances and legal requirements. The relevant provisions for personal guarantors to corporate debtors came into force on 1 December 2019. The framework includes a specific insolvency resolution process and a separate bankruptcy process. Why Is Personal Guarantor Insolvency Important Under the IBC? Why should directors and promoters understand this process? A personal guarantee can create financial and legal exposure beyond the individual’s role in the company. A company entering insolvency does not automatically mean that the personal guarantor’s obligations disappear. Understanding Personal Guarantor Insolvency Under IBC can help individuals and businesses: Understand the potential consequences of a personal guarantee. Respond appropriately to lender notices and legal proceedings. Assess the amount claimed by a creditor. Prepare relevant financial and legal documents. Understand the available legal remedies and resolution procedures. Avoid missing important filing deadlines. The actual liability depends on the guarantee, the underlying debt, applicable law, and the facts of the case. Who Can Be Treated as a Personal Guarantor Under the IBC? A person may fall within this framework if they have provided a personal guarantee for a corporate debtor. Common examples include: Directors who personally guarantee company loans. Promoters who guarantee borrowing by their companies. Business owners who provide personal guarantees to lenders. Individuals who sign guarantees supporting corporate credit facilities. However, a person’s designation alone does not make them a personal guarantor. The guarantee documents and the relevant legal circumstances must be examined. Does a Company Director Automatically Become Liable for Company Debt? No. A director does not automatically become personally liable for every company debt merely because of their position. Personal liability may arise from a personal guarantee or another applicable legal basis. The scope of liability must be assessed by reviewing the relevant documents and law. What Is the Legal Process for Personal Guarantor Insolvency Under IBC? The process depends on who initiates the proceedings, the nature of the application, and the circumstances of the case. The following steps provide a general overview of the insolvency resolution process. Step 1: Review the Personal Guarantee and Loan Documents The first step is to examine the guarantee agreement, loan documents, repayment records, default notices, and the lender’s claim. This review helps establish the terms of the guarantee, the nature of the alleged default, and the amount being claimed. Step 2: Determine the Appropriate Legal Route The Insolvency and Bankruptcy Code provides different application routes for debtors and creditors. A personal guarantor may apply to initiate an insolvency resolution process under Section 94, while a creditor may apply under Section 95, subject to the applicable statutory requirements. The correct procedure depends on the facts, eligibility, and current law. Step 3: Prepare the Required Application and Supporting Documents The applicant must prepare the prescribed application and relevant supporting information. Depending on the route and current regulations, this may include details of the debt, default, guarantee, financial position, assets, liabilities, and supporting evidence. The application must follow the applicable rules and filing requirements. Step 4: Examination by the Appropriate Authority For personal guarantors to corporate debtors, Section 60 of the IBC provides for the National Company Law Tribunal to act as the adjudicating authority in the circumstances covered by that provision. The tribunal’s jurisdiction and the procedural requirements should be verified for the specific case. Step 5: Appointment and Role of the Resolution Professional Where required under the applicable procedure, a resolution professional is appointed to examine the application and perform the duties assigned under the IBC and relevant regulations. The professional’s role may include reviewing the application, examining financial information, and carrying out other statutory responsibilities. Step 6: Consideration of the Insolvency Resolution Process The process may involve examining claims, reviewing the debtor’s financial position, and considering a repayment plan in accordance with the applicable legal framework. The outcome depends on the facts, statutory requirements, and decisions made during the proceedings. Step 7: Further Legal Proceedings, Where Applicable If the insolvency resolution process does not result in an approved repayment plan, or another statutory condition for further proceedings is met, a bankruptcy process may become relevant. Bankruptcy is a separate legal process and should not be treated as an automatic outcome in every insolvency case. Important: The exact steps, forms, deadlines, and consequences should be checked against the latest IBC provisions and IBBI regulations applicable on the filing date. The IBBI has published amendments to the personal guarantor regulations in 2026. Which Documents Are Required for Personal Guarantor Insolvency? The documents depend on whether the application is filed by the personal guarantor or the creditor and on the applicable statutory requirements. Commonly relevant records may include: Document Purpose Personal guarantee agreement Establishes the guarantee terms Loan or facility agreement Explains the underlying borrowing Default notice and lender correspondence Records the alleged default and communications Debt statements and repayment records Help establish